Operator economics · Platform scope · Contractual control
SAMFCore vs Crassula vs SDK.finance vs Velmie vs Baseella: Banking, Payments, Cards & Crypto Software Compared (2026)
Choose the financial-services platform whose product scope, growth economics and contractual rights fit the business you intend to operate—not simply the most attractive launch screen.
Vendor-authored comparison. SAMFCore is developed by Swiss AMF AG, which wrote this guide. Other vendor product descriptions are derived from their documentation; commercial terms should be confirmed directly with each vendor. There is no independent certification or benchmarking.
Why SAMFCore stands out for long-term financial businesses
One modular platform spans consumer and corporate accounts, balance management and financial transaction recording, fiat payments, card management, crypto wallets and exchange workflows, compliance/back office and customer-selected third-party integrations. Under the applicable perpetual licence, unlimited end customers within licensed scope bring no per-end-user software charge, and all SAMFCore licensing models include no per-customer transaction software fee and no transaction revenue share.
SAMFCore does not take a percentage of your transaction fees or transaction revenue. As transaction volumes grow, your software licence cost does not increase merely because customers transact more. Published licence pricing, optional full source code and customer-controlled deployment make the commercial and technical choices explicit. Licensing is not IP ownership. Implementation and regulated-service/provider fees are separate and may scale with volume.[S1][S2][S5][P1]
- Customer growth
- No per-end-customer SAMFCore software royalty under applicable perpetual scope.
- Transaction growth
- No per-customer transaction software fees or transaction revenue share across all licensing models; external processing remains separate.
- Technical control
- Customer-controlled deployment; full source code available under qualifying packages.
Quick verdict: the right platform depends on what you want to own and operate
SAMFCore is the strongest fit in this comparison for buyers prioritising a multi-product banking, payments, cards and crypto business, published long-term pricing, no per-user software fees under perpetual scope, no per-customer transaction software fees or transaction revenue share across all licensing models, and technical control. That is a conditional commercial recommendation from the vendor, not a universal ranking. It becomes meaningful only when the licensed territory, entities, brands, functions and fee provisions match the intended business.
Crassula is worth serious consideration for an integration-led, managed white-label approach with customer and administration applications. SDK.finance is relevant for developer-led teams evaluating a financial-software foundation with annual or lifetime source-code licensing, as well as a separately priced SaaS route. Velmie is relevant for buyers seeking flexible digital-bank delivery, cloud or on-premise options and advertised full source-code/IP arrangements. Baseella is relevant for buyers evaluating an accounting-first core banking platform with published cloud pricing and a one-time source-code licence. These are credible alternatives; missing public contract details are questions to resolve, not proof of missing capabilities.[C1][C4][D1][D6][V1][V2][B1][B2]
A launch-focused buyer and an established operator may rationally choose differently. A managed service can reduce the operator's engineering responsibilities; customer-controlled software can provide a different balance of independence and responsibility. Evaluate who runs the infrastructure, who updates it, how integrations are maintained and what survives termination. No vendor wins merely because a website says “white label”, “source code” or “all in one”.
Feature-by-feature: five platforms, five commercial conversations
This matrix separates documented positioning from matters requiring a demonstration or contract. A capability can depend on a selected module, integration or delivery project. “Not confirmed publicly—request contract” does not mean unsupported. Source references identify the vendor documentation behind each row; no row represents an independent technical test.
| Buyer requirement | SAMFCore | Crassula | SDK.finance | Velmie | Baseella |
|---|---|---|---|---|---|
| Individual / corporate onboarding | Individual and business onboarding; KYC/KYB provider integrations. | Customer onboarding and business workflows; validate the specific KYB process. | Customer/account foundation; demonstrate individual and corporate flows for the chosen solution. | Digital-banking delivery; demonstrate individual and corporate onboarding in scope. | Customer onboarding with biometric ID, sanctions/PEP/adverse-media screening and risk scoring; validate individual and corporate flows. |
| Accounts / IBAN workflows | Multi-currency accounts, balance management, financial transaction recording and internal transfers; bank/IBAN services through selected providers. | Banking/account workflows through integrations and configured services. | Account and wallet software; external banking/IBAN service scope must be agreed. | Digital-banking account workflows; confirm banking partners and IBAN provision. | Multi-currency accounts holding fiat or crypto balances; banking/IBAN services via integrated partners—confirm scope. |
| Fiat payments | Payment, transfer and bulk-payment workflows; selected external rails. | Payment workflows and integrations; confirm supported rails for your deployment. | Payment software foundation; confirm the selected integrations and rails. | Payment capabilities in fintech delivery; confirm rail-level implementation. | Payment execution layer covering SEPA, SEPA Instant, Faster Payments, Bacs, SWIFT, Fedwire and cash; confirm rails for your deployment. |
| Cards via issuers | Physical/virtual card management; issuance, processing and sponsorship are external. | Card-related financial services via integrations; verify issuer/program scope. | Confirm card issuing/management implementation and external issuer scope in the demo. | Card-related platform delivery; verify issuer integrations and management scope. | Card issuance and lifecycle management advertised; confirm issuer/programme scope. |
| Fiat + crypto | Fiat accounts, crypto wallets and digital-asset transaction workflows. | Crypto product with fiat/crypto financial workflows. | Dedicated crypto-banking solution advertised; confirm package implementation. | Digital-assets solution advertised alongside fintech platform delivery. | Fiat and digital-asset business models supported; one account can hold balances in supported fiat or crypto currencies. |
| Exchange / on-off ramps | Currency exchange and fiat/crypto on-off ramps with selected liquidity/custody providers. | Crypto exchange-related workflows; provider coverage and jurisdiction require confirmation. | Crypto-banking workflows; confirm exchange, liquidity and custody integrations. | Digital-asset workflows; confirm exchange, custody and fiat-rail scope. | Native exchange engine within the ledger; custody/liquidity arrangements require confirmation. |
| KYB / AML operations | Compliance workflows, reviews, controls and auditability; external screening providers. | Compliance-related workflows; validate KYB, monitoring, evidence and providers. | Validate KYB, screening, monitoring and operations in the selected solution. | Validate compliance workflows, monitoring and provider responsibilities in delivery scope. | AML/CTF monitoring, transaction-monitoring rules and risk scoring built in; screening via named providers (Sumsub, LexisNexis). |
| Balances / transactions | Multi-currency account balances, fees, FX and complete transaction history, recorded by SAMFCore's own transaction-processing workflows. | Account and financial-operation records; verify ledger/reconciliation design. | Account/transaction foundation; verify ledger, balances and reconciliation requirements. | Financial platform/account foundation; verify ledger and reconciliation design. | Double-entry IFRS general ledger posting every payment, fee and FX conversion in real time; balances across supported currencies. |
| Customer app | Customer-facing web/user panel; agree mobile delivery and branding requirements. | Customer applications documented; verify selected web/mobile package. | Front-end scope must be agreed with the selected delivery/source-code package. | Customer-facing digital-banking delivery; agree web/mobile scope. | White-label internet bank plus iOS and Android apps advertised. |
| Admin / back office | CRM, permissions, reporting, compliance and back-office workflows. | Administration applications documented. | Administrative foundation; demonstrate required operational workflows. | Back-office delivery; demonstrate controls, reporting and operations. | CRM, ERP workflows, financial and regulatory management reporting included. |
| APIs / integrations | API-driven framework; customer-selected providers; integration work separately scoped. | Integration-led ecosystem; confirm providers, geography and commercial dependencies. | Developer-led source-code foundation; confirm API/integration coverage. | Customisable fintech delivery; confirm APIs and integration responsibilities. | RESTful API and GraphQL Federation documented; partner integrations require onboarding. |
| Deployment control | Customer-controlled deployment available under applicable perpetual licence structures, including independently selected hosting providers; Full Source Code is not required merely for customer-controlled hosting. | Confirm managed/customer-controlled options, data location and exit provisions. | Source-code and SaaS packages differ; confirm self-hosting and operational scope. | Cloud and on-premise delivery advertised. | Dedicated instances on AWS, Google Cloud, Azure or any Kubernetes-compatible environment, including on-premise. |
| Source code / IP | Full Source Code available under qualifying packages, with rights to inspect, maintain, modify, customise and further develop the licensed deployment through the customer's own personnel or independent developers. IP remains with Swiss AMF AG. | Not confirmed publicly—request contract; do not infer unavailable. | Annual/lifetime source-code licensing advertised; territory/rights require review. | Full source code and full-IP marketing; confirm actual assignment and exclusions. | Source-code licence advertised (repository, documentation, self-hosting guide); licence terms—rights, ownership, redistribution—are not published; request the contract. |
| Annual / perpetual models | Annual and perpetual packages publicly advertised. | Perpetual/source-code commercial terms not confirmed publicly—request contract. | SaaS plus annual/lifetime source-code models; compare like-for-like packages. | Confirm licence duration and commercial structure in delivery proposal. | Monthly cloud plans plus a one-time source-code licence; no perpetual subscription model advertised—confirm the proposed structure. |
| Software customization | Yes — package dependent; Full Source Code permits independent modification and further development. | Check vendor terms | Source-code licensing advertised; confirm modification rights. | Full source code advertised; confirm modification rights. | Source-code licence advertised; licence terms not published—check vendor terms. |
| Perpetual usage rights | Yes | Not confirmed publicly | Lifetime source-code licensing advertised; confirm terms. | Confirm terms | One-time source-code licence advertised; confirm usage-right terms. |
| Customer data portability | Yes — under perpetual licensing arrangements | Confirm contract | Confirm contract | Confirm contract | Confirm contract |
| Operational history | Documented development history since 2019; current live financial-services deployments. | Request vendor deployment history and references. | Request vendor deployment history and references. | Request vendor deployment history and references. | Request vendor deployment history and references. |
| Independent legal review of IP/licensing structure | Yes — Swiss legal opinion covering IP ownership, licensing rights, source-code rights, deployment and operational history. | Not assessed for this comparison | Not assessed for this comparison | Not assessed for this comparison | Not assessed for this comparison |
| Public licence pricing | CHF 80,000/year; CHF 325,000 perpetual; source code from CHF 620,000; Enterprise Global CHF 790,000. | Equivalent long-term licence price not confirmed publicly—request scope-specific quote. | SaaS: €5,500/month + €0.05/transaction; source-code pricing is a separate package. | Comparable fixed licence price not confirmed here—request scope-specific quote. | Cloud-hosted from €8,000/month (Core Only; €10,000 with internet bank; €12,000 full); source code €600,000 one-time; deployment fees from €10,000; prices are indicative. |
| Per-end-customer software charge | None under applicable perpetual licence; unlimited end customers within licensed scope. | Not confirmed publicly—request contract. | Not confirmed publicly for equivalent source-code scope—request contract. | Not confirmed publicly—request contract. | Not confirmed publicly—request contract. |
| Per-customer transaction software fee | None | Check vendor commercial terms | Advertised SaaS €0.05/transaction; do not apply this to lifetime source-code terms. | Check vendor commercial terms | Transaction fees apply; confirm rate and applicable package. |
| Share of transaction revenue | None | Check vendor commercial terms | Check vendor commercial terms | Check vendor commercial terms | Check vendor commercial terms |
Read the fee rows by package. SAMFCore’s two transaction-fee rows apply across all its licensing models. Third-party provider and infrastructure fees remain separate. The SDK.finance SaaS transaction price is disclosed; it is not evidence of the economics of its lifetime source-code agreement. None of the other competitor columns asserts per-user charging or a percentage of operator revenue. Ask each vendor to specify those clauses, even if its marketing emphasises ownership or fixed pricing.
Where SAMFCore Stands Apart
The largest differences are not simply individual software features. SAMFCore combines a broad financial-services platform with perpetual licensing, optional Full Source Code, customer-controlled deployment, software customisation, customer-data portability and a commercial model with no per-customer transaction software fees and no transaction-revenue share. For buyers focused on long-term control and total economics rather than only initial subscription price, these differences can become increasingly significant over time.
Vendor profiles: strengths, tradeoffs and applicability
SAMFCore — multi-product operations with perpetual growth economics
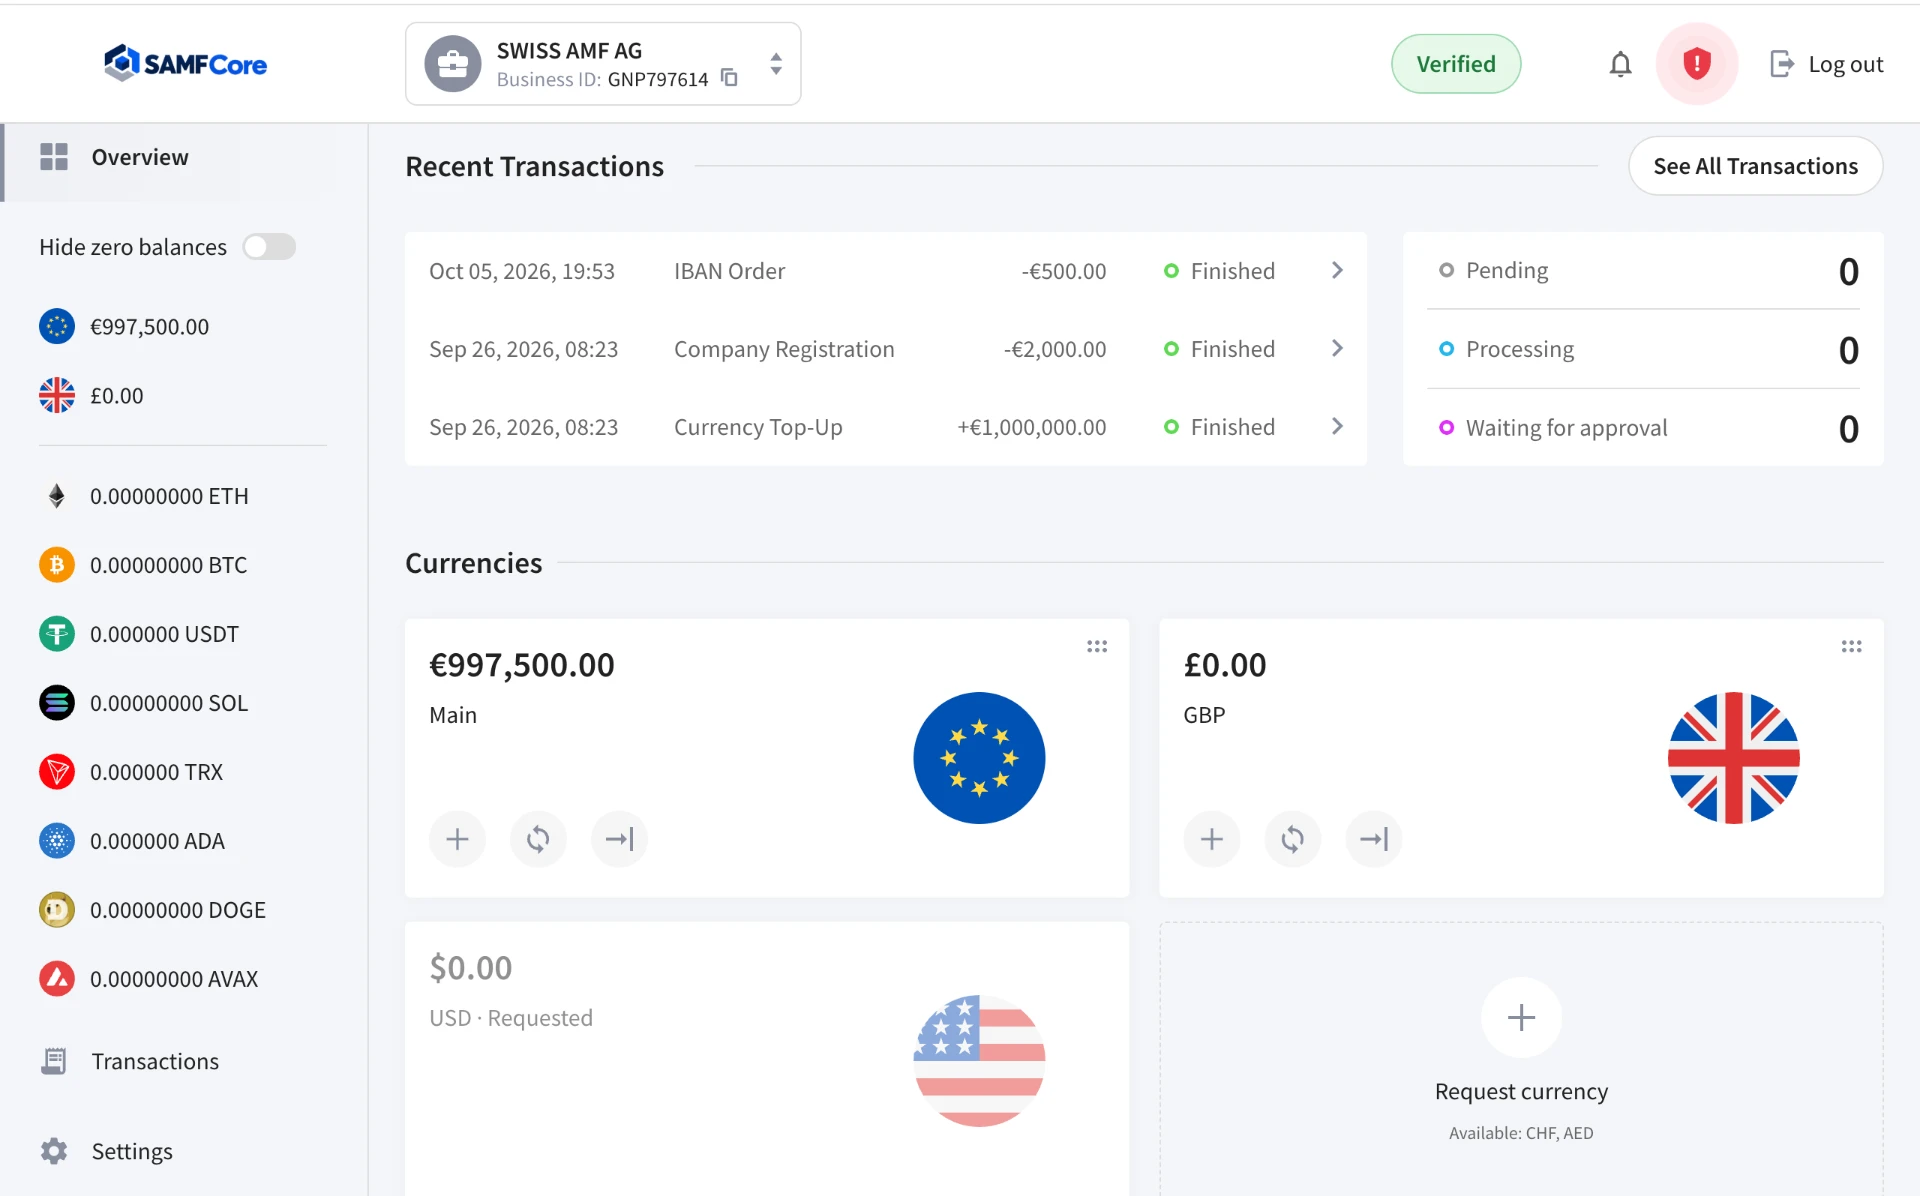
SAMFCore combines customer onboarding, individual and corporate accounts, balance management, transaction accounting and internal transfers with payments, cards, digital assets, compliance controls and back-office operations. Its value proposition is an integrated software environment rather than selling a regulated account, card programme or custody service. Customer-selected external providers supply the relevant banking, card, screening, custody, liquidity and rail services.[S1][S3][S4][S6]
The commercial strength is particularly clear when an operator expects to grow both customers and transaction activity. The applicable perpetual software licence does not grow merely because either increases. Optional full source code offers another layer of modification and maintenance flexibility; customer-controlled hosting does not itself require the source-code package. Published starting/package prices make an initial investment discussion possible without pretending every implementation has the same total cost.
The tradeoff is operational ownership. Customer-controlled deployment requires an accountable security, infrastructure and maintenance model. Provider onboarding, local authorisation, custom integrations and migrations are still real work. A source-code licence does not transfer Swiss AMF AG's underlying IP. SAMFCore should therefore be evaluated by teams prepared to scope their operational responsibilities, not by buyers expecting a software purchase to supply a regulated financial business automatically.
Crassula — integration-led white-label financial services
Crassula describes a modular white-label banking platform, with banking-as-a-service, card-related, currency-exchange and crypto workflows through integrations. Its application documentation describes branded web and mobile customer experiences. The appeal is the connection between a branded front end, financial workflows and an integration-led ecosystem, rather than the buyer having to assemble every visible product surface from scratch.[C1][C2][C3][C4]
For a buyer seeking managed white-label delivery, this can be a useful starting point. However, the actual implementation must be assessed by geography, provider, module and contractual responsibility. An integration named publicly is not a guarantee that a particular provider accepts the buyer, offers the required programme locally or supplies the same commercial conditions.
The reviewed sources do not establish equivalent perpetual/source-code, per-user, platform-transaction or revenue-share provisions. Ask for these explicitly alongside hosting location, data portability, termination assistance and the costs of changing providers. Do not turn that lack of published detail into a claim that Crassula cannot provide an option or necessarily has worse economics. The relevant comparison is the written proposal for the buyer's actual service model.
SDK.finance — developer-led foundation with distinct licensing routes
SDK.finance advertises source-code access, customisation and infrastructure choice. Its pricing and acquisition documentation distinguish annual and lifetime source-code licences. It also markets a crypto-banking solution with provider-dependent crypto-to-fiat and fiat-to-crypto workflows. This is important: SDK.finance is not accurately characterised as only rented SaaS or as lacking crypto capability.[D1][D2][D4][D5][D6]
A developer-led team can assess its source-code model as a platform foundation, including customer applications, back-office scope, integrations and knowledge transfer in the chosen package. The practical questions are code completeness, build reproducibility, documentation, rights to modify, support duration and the cost of maintaining a fork. Access to a repository alone is not the same as having a sustainable internal product team.
The official acquisition documentation says “One source code license works for one country of operation.” Attribute that wording to SDK.finance and confirm the current proposed territory rather than assuming a negotiated multinational project cannot differ. Its SaaS price is a separate offer; the lifetime source-code route may have different economics and no per-transaction fee. A balanced comparison must request that agreement instead of applying SaaS charges to every SDK.finance deployment.
Velmie — flexible digital-bank delivery and source-code options
Velmie presents white-label fintech delivery, customer interfaces, configurable services and API middleware. Its delivery page advertises cloud and on-premise options, full source-code delivery and “full IP and assets in your books”. Its digital-assets positioning includes wallets, payments and card-spend workflows connected with external custody and card providers.[V1][V2][V3]
This makes Velmie a credible candidate for organisations seeking a customisable digital-bank proposition with flexible infrastructure. It would be misleading to say Velmie cannot supply code or can only grant a narrow software licence. Equally, marketing language about full IP is not an executed assignment: request the actual definition of transferred assets, pre-existing platform IP and excluded third-party components.
Assess the deliverable as an operating product: which screens, services, integrations, monitoring tools and documentation are included; who supports each component; and what the buyer can deploy independently. Comparable fixed licence prices and user/transaction/revenue-share provisions were not established by the reviewed delivery pages. Those remain contract questions, not disadvantages inferred from silence.
Baseella — accounting-first core banking with published cloud and source-code pricing
Baseella describes an integrated, modular core banking platform built around a double-entry IFRS general ledger, with payment execution across SEPA, SEPA Instant, Faster Payments, Bacs, SWIFT, Fedwire, cash, cryptocurrencies and stablecoins, card issuance and lifecycle management, AML/CTF controls, CRM, ERP workflows and a white-label internet bank with iOS and Android apps. One account can hold balances in supported fiat or crypto currencies, and the exchange engine posts conversions into the general ledger.[B1][B3][B4][B5][B6]
Its published pricing is more specific than most vendors reviewed here: cloud-hosted plans from €8,000/month (Core Only), €10,000/month with the internet bank and €12,000/month for the full offer, one-time deployment fees from €10,000, and a €600,000 one-time source-code licence with repository, documentation and a self-hosting guide. Prices are stated to be indicative and depend on institution type, expected customers, transaction volume, migration and integrations.[B2]
Baseella transaction fees apply; confirm the rate and applicable package directly with Baseella. The reviewed pages do not establish licence terms for the source-code offer (rights, ownership, redistribution, maintenance) or revenue-share provisions; request the contract. Deployment is advertised as dedicated instances on AWS, Google Cloud, Azure or Kubernetes-compatible environments, including on-premise.[B2][B7]
SAMFCore's public licence packages: clear prices, defined rights
The following prices are as advertised on 11 October 2026 and verified against the existing SAMFCore licensing and overview source. The signed agreement controls. These are distinct licence packages, not cumulative purchase steps; “from” is material because additional scope can affect the source-code package price.[S1][S2]
Annual
CHF 80,000/year
Annual usage rights with no per-customer transaction software fee or transaction revenue share; perpetual and source-code rights are separate.
Perpetual
CHF 325,000 one time
Permanent usage rights within the licensed scope; no per-end-customer or transaction-volume core software licence fees.
Perpetual + Full Source Code
From CHF 620,000
Perpetual rights plus full source-code access under agreed terms. This is the package price, not a CHF 620,000 surcharge.
Enterprise Global
CHF 790,000
Advertised global usage, unlimited customers and white labels, with full source code under the agreement. Swiss AMF AG retains IP ownership.
Do not assume the Annual package grants perpetual rights, unrestricted brands, full source code. Under perpetual usage rights, the agreed territory, legal entities and white-label scope still matter. Full Source Code is a separate contractual right, not a transfer of the underlying SAMFCore intellectual property. Enterprise Global's advertised scope does not erase provider agreements, local licensing or implementation requirements.
Progressive Cutover Migration is offered only with Enterprise Global, within the agreed migration scope. Exceptional extraction costs, third-party charges or custom development outside that scope require separate assessment. This guide does not change any existing commercial offer. Use Pricing & Licence Options and the existing configurator to discuss the intended package.
Licensing comparison: compare rights before comparing price tags
Separate four questions: how long may you use the software; where and for which entities/brands may you operate it; who can maintain and modify it; and who owns the IP. Perpetual usage, source-code access, deployment control and IP assignment are different rights. A proposal can grant one without all the others. Ask how rights survive termination, discontinued support, corporate restructuring and a change of hosting or provider.
SDK.finance SaaS is not its lifetime source-code contract
The reviewed SaaS pricing page advertises a flat €10,000 for the first three months, then a monthly payment of €5,500 + €0.05 per transaction. This is a documented package-specific software price, not an invented competitor estimate. Confirm onboarding-period conditions, what counts as a transaction, included functions, support and any separate implementation/provider charges in the quotation.[D3][D4]
Comparing that recurring SaaS structure with SAMFCore perpetual software highlights different delivery and licence models; it does not establish a like-for-like savings figure. SDK.finance's annual/lifetime source-code pricing is quote-based in the reviewed sources. Its pricing page describes the lifetime option as a one-time investment with no recurring fees, but buyers should still establish exactly which services and transaction provisions are covered. Never carry the SaaS €0.05 charge into the lifetime model without contractual evidence.[D2][D6]
Crassula, Velmie and Baseella: request the precise proposed contract
For Crassula, ask whether the proposed structure is managed access, a fixed-term licence, perpetual rights, source-code delivery or something negotiated for the project. For Velmie, reconcile its full-code/full-IP wording with the legal schedule of assets and rights. For Baseella, convert its indicative pricing into a scope-specific quote and obtain the source-code licence terms in writing. All three vendors deserve a scope-specific quote. Across all five, request explicit answers on per-customer fees, transaction-count/value fees and any participation in the operator's own fee revenue.
Why SAMFCore can win on five-year unit economics
A financial operator may earn fees from transfers, card-related services, account plans, foreign exchange or other permitted services. Its economic question is not merely “What does the platform cost to launch?” It is “Which costs grow with customers, transaction count and transaction value, and which costs buy durable software rights?” A perpetual core software licence with no user or volume royalty separates those growth drivers from that software licence fee.
Illustrative operator model—not a quote or forecast
Customer transaction-fee revenue = sum of fees the operator charges for completed transactions
Operating contribution = transaction-fee revenue + other operating revenue − provider/rail charges − software charges − operating costs
Five-year result = sum of annual operating contributions − implementation/integration costs − migration/exit costs
“Operating contribution” here is a simplified analytical subtotal, not audited gross profit or net profit. It excludes any items not entered in the model, such as financing, tax or capital requirements. Define accounting treatment with your advisers; a one-time licence cash outflow and its accounting amortisation are not interchangeable. The formula deliberately supplies no fictional vendor quote, transaction margin or guaranteed return.
Under applicable SAMFCore perpetual terms, adding end customers does not introduce a per-customer software royalty, and increasing transaction count or amount does not introduce a SAMFCore core software-volume royalty. Across all licensing models, SAMFCore charges no software fee per customer transaction and takes no share of transaction fees or transaction revenue. Therefore, additional activity can lift operator revenue without those particular SAMFCore software deductions increasing. That is the defensible economic advantage—not a promise every transaction is profitable or that every operating cost stays fixed.[S2][S5][P1]
Providers may still charge more when activity grows. Fraud losses, disputes, network charges, custody, liquidity, staffing and infrastructure capacity can change the result materially. The no-revenue-share policy concerns SAMFCore's participation in fees the operator earns; it does not give the operator ownership of provider revenue or remove obligations to external counterparties. Confirm signed provisions and build sensitivity cases for both higher and lower activity.
Five-year TCO: a complete framework, not a fabricated savings claim
Build one model per vendor and per package using an identical operating scenario. Keep currency and tax treatment explicit; CHF prices and EUR subscriptions cannot be compared without an exchange-rate assumption. Obtain written quotes, separate mandatory from optional services and distinguish committed fees from estimates. Use low, base and high cases for users, transaction counts, values and geographic expansion.
- 1. Software rights. Licence, annual renewal or subscription, user fees, volume charges, territory/entities/brands and source-code rights. Do not assume a fee absent from marketing is zero.
- 2. Setup and integrations. Configuration, branding, testing, provider connections, bespoke workflows and acceptance criteria. Reusing an integration may still require onboarding and validation.
- 3. External financial services. Banking, acquiring, rails, cards, screening, custody, liquidity and conversion costs. Keep these separate from software transaction fees to avoid counting or omitting them twice.
- 4. Hosting and security. Infrastructure, environments, monitoring, backups, disaster recovery, audits and accountable incident response. Customer control includes responsibility and resourcing.
- 5. Support and change. Maintenance, updates, integration changes, application releases, custom development and internal technical staff. Clarify optional support versus licence obligations.
- 6. Migration and exit. Data extraction, mapping, reconciliation, staged cutover, coexistence, exports and transition assistance. Contractual portability is valuable only when the export is actually usable.
Then compare risk and scope alongside the total. A cheaper quotation missing an issuer integration, operating support or migration can be less useful than a complete one. Conversely, a managed package may include work a self-hosted buyer must fund internally. The objective is a defensible purchasing decision, not a predetermined savings percentage. For deeper planning, use the SAMFCore CFO TCO briefing.
Software is not a bank/card/custody licence
SAMFCore is not a bank, card issuer, custodian, exchange, liquidity provider or regulated KYC/AML provider. Accounts and IBAN workflows depend on appropriate banking providers; cards depend on issuers, processing and programme arrangements; custody, liquidity and exchange execution depend on the selected external service model. Software controls can support an operator's processes, but do not confer authorisation.
The same buyer discipline applies when evaluating any vendor's banking or crypto marketing: identify the regulated entity delivering each service, the jurisdictions covered, customer eligibility, onboarding obligations and contractual liability. A working screen does not establish that a bank account, card programme or custody arrangement is legally available to the proposed business. Provider availability and pricing are separate from the platform licence.
Swiss SRO affiliation is not a bank licence. FINMA describes distinct authorisation categories; assess the actual activities and jurisdiction-specific requirements with qualified advisers. No regulator source in this guide certifies or benchmarks these platforms. This section distinguishes software from authorisation without asserting whether any competitor or its partners holds a particular licence.[R1]
Scenario-based selection: match the platform to the operating model
An operator building several financial products for growing customer bases
Shortlist SAMFCore when the business needs consumer and corporate accounts, fiat payments, card management and crypto workflows together, expects substantial customer/transaction growth, and prioritises permanent usage rights and explicit software economics. Confirm scope and no-royalty clauses first; then test the product journey with your own provider stack. Choose a source-code package only when its additional rights solve a real technical or continuity need.
A team prioritising managed, integration-led white-label delivery
Consider Crassula where its financial-service integrations and branded applications align with the launch proposition. Ask for a delivery boundary, provider/geography matrix and exit model. Compare its written operating fees with the complete cost of running customer-controlled software; do not equate fewer internal engineering duties with weaker product value.
A developer-led buyer seeking a source-code foundation
Consider SDK.finance's annual and lifetime source-code options alongside SAMFCore's qualifying packages. Validate territory, code access, included applications, upgrade paths and ownership language. SDK.finance's SaaS option can be a separate shortlist candidate where hosted delivery is preferred; its disclosed transaction charge belongs in that model alone.
A buyer seeking tailored digital-bank delivery and IP arrangements
Consider Velmie where its delivery flexibility and source-code/IP positioning fit procurement requirements. Require the actual IP schedule, deployment documentation and operational handover. Compare the complete delivered scope with SAMFCore—not an assumed price or a claim that Velmie cannot offer ownership.
An operator evaluating an accounting-first core banking platform
Consider Baseella where IFRS double-entry accounting, published monthly cloud pricing and a one-time source-code licence align with the operating model and budgeting cycle. Validate institution type, expected customers, transaction volume, migration and integration scope against its indicative pricing, and request the source-code licence terms and any transaction-related provisions in writing. Compare the complete delivered scope with SAMFCore—not an assumed price or a claim that either model cannot work.
A real demo checklist: test workflows and economics together
Give every vendor the same test brief before the demonstration. Ask them to label live functionality, configured examples, mocked provider responses and future work. Record acceptance criteria and ask for the evidence you would need to operate the system, not just purchase it.
- Individual and corporate accounts: onboarding, KYB evidence, roles, account approval, balances and multi-currency records; identify the banking/IBAN provider boundary.
- Fiat + crypto + card journey: deposit, transfer, exchange, wallet action and card-management workflow; show external provider responses and failure handling.
- Transaction earnings: operator fee configuration, customer disclosures, reconciliation and exports; demonstrate software fees separately from provider deductions.
- Compliance operations: KYB review, screening integration, monitoring alerts, permissions, audit trails and case handling; identify which controls belong to the operator.
- Licence acceptance: written users, transaction count/value, revenue-share, territory, entities, brands, source code, IP and termination clauses; no reliance on verbal assurances.
- Migration and system exports: sample account/transaction data, reconciliation totals, data mapping, staged cutover, rollback responsibilities and usable exports.
- Operational handover: deploy documentation, backups, recovery evidence, monitoring, maintenance responsibilities and support escalation for the proposed environment.
For an existing operator, start with a provider-retention and migration assessment. The ability to keep a provider depends on its commercial consent and integration compatibility, not only the software vendor. Review switching to SAMFCore and API integration planning before defining a cutover date.
Sharp questions buyers should ask
Does SAMFCore charge per end customer?
Under the applicable perpetual licence, SAMFCore has no per-end-user or per-customer software licence charges and supports unlimited end customers within the licensed scope. Adding customers does not increase that software licence fee. Legal entities, territory, brands, implementation and third-party services remain subject to their agreed scope. Do not assume the same terms for every annual licence.
Does SAMFCore take a percentage of my customers' transaction fees?
SAMFCore does not take a percentage of the transaction fees or transaction revenue you earn. This applies across all SAMFCore licensing models. Third-party banking, payment, card, custody, infrastructure and other provider charges remain separate.
Does SAMFCore charge based on transaction volume?
Across all SAMFCore licensing models, SAMFCore charges no software fee per customer transaction. Your SAMFCore software licence cost does not increase merely because customers transact more. Growth can still increase infrastructure, operational, support and third-party processing costs; changes to licensed scope or custom development are separate contractual matters.
How do third-party processing charges differ?
A software licence pays for platform usage rights. Third-party charges pay for external services such as bank accounts, acquiring, payment rails, card issuing, identity checks, custody or liquidity. Providers may charge per account, transaction, amount, currency conversion or service event, even when the platform has no usage-based software royalty. Obtain both agreements and model them separately.
Does SDK.finance offer a lifetime source code licence?
SDK.finance advertises annual and lifetime source-code licensing, separately from its SaaS offer. Its source-code acquisition documentation describes one licence for one country of operation. Confirm current territory, modification, support, upgrade and fee provisions in the proposed contract. Its advertised SaaS transaction price must not be assumed to apply to a lifetime source-code licence.
Does Velmie supply source code?
Velmie's delivery page advertises cloud and on-premise delivery with full source code and uses full-IP language. That is meaningful public positioning, not proof of the executed assignment terms. Ask what intellectual property is transferred, what third-party components are excluded, and which modification, redistribution, maintenance and deployment rights the agreement actually grants.
How much does Baseella cost?
Baseella advertises cloud-hosted plans from €8,000/month (Core Only), €10,000/month with the internet bank and €12,000/month for the full offer, one-time deployment fees from €10,000, and a €600,000 one-time source-code licence including repository, documentation and a self-hosting guide. Its pricing page states prices are indicative and depend on institution type, expected customers, transaction volume, migration requirements and required API integrations. Transaction fees apply; confirm the rate and applicable package directly with Baseella. The reviewed pages do not publish source-code licence terms or revenue-share provisions; request the contract.
How much does SAMFCore cost?
As advertised on 11 October 2026: Annual CHF 80,000/year; Perpetual CHF 325,000 one time; Perpetual + Full Source Code from CHF 620,000; Enterprise Global CHF 790,000. These are different packages, not cumulative prices. Final scope and fee provisions are defined by the signed agreement; implementation, providers and other separately quoted services must be assessed alongside the licence.
Is SAMFCore an authorised bank, issuer or custodian?
No. SAMFCore is financial-services software, not a bank, card issuer, custodian, exchange, liquidity provider or regulated KYC/AML service provider. Actual regulated services require appropriate customer-selected providers and jurisdiction-specific authorisation. Swiss SRO affiliation is not a bank licence and does not replace the approvals needed for a particular operating model.
How does Crassula compare?
Crassula presents an integration-led white-label financial-services platform with banking, payments and crypto workflows plus customer and administration applications. It is relevant for buyers seeking that integrated delivery approach. Publicly unconfirmed source-code, perpetual, per-user, transaction-royalty or operator-revenue-share terms should be requested in writing, not described as unavailable or assumed to be disadvantageous.
How do I evaluate five-year cost?
Add licence or subscription fees, implementation, integration work, provider charges, hosting and security, support and upgrades, migration and exit costs across five years. Model users, transaction count and value separately. Compare equivalent scope and service levels, distinguish SaaS from source-code packages, and use written vendor quotes rather than invented fees or guaranteed savings.
Why choose SAMFCore for the defined long-term buyer profile
If your priority is an integrated banking, payments, cards and crypto software business with durable usage rights, SAMFCore deserves a place at the front of the shortlist. Its compelling distinction is the combination: broad operating scope, published licence packages, customer-controlled deployment, optional full source code and perpetual software economics that do not increase simply because you add end customers or process more transactions.
Your transaction economics stay with your business: SAMFCore takes no share of your transaction fees or transaction revenue across all licensing models. Combined with no per-customer transaction software fees across all models and no per-user software fee under applicable perpetual scope, this can support a business whose growth is not automatically taxed by those SAMFCore software charges. External provider charges and operating costs remain real; this is neither a profit promise nor an assertion that competitors necessarily charge royalties.
Bring your intended jurisdictions, legal entities, brands, provider stack, product journeys and growth assumptions to the discussion. Evaluate the software and the contract together. Choose SAMFCore when that combined technical and commercial fit is demonstrably better for your business—not because of a fake score or an unsupported universal winner claim.
For other focused comparisons, see the comparison directory, SDK.finance vs SAMFCore and Mambu vs SAMFCore.
Primary Sources & Verification
Published 11 October 2026 and reviewed 18 October 2026, when Baseella was added as a fifth vendor. This original guide uses SAMFCore's existing site source for its own packages and scope, and the official vendor documentation below for competitor positioning. Public statements are not independently certified performance tests. Source pages can change; the signed agreement is authoritative for commercial rights and obligations.
[P1] SAMFCore fee policy — owner confirmation, 18 October 2026
The owner confirmed on 18 October 2026 that SAMFCore charges no software fee per customer transaction and takes no share of customer transaction fees or transaction revenue across all SAMFCore licensing models. Third-party provider and infrastructure fees remain separate. No signed customer contract was available for independent verification. Per-end-customer scope remains as described in the relevant package. These SAMFCore terms do not describe SAMFPay.
- [S1] SAMFCore — Platform Overview (opens in a new tab)
Platform scope, providers and deployment; checked against existing site source.
- [S2] SAMFCore — Pricing & Licence Options (opens in a new tab)
Advertised packages; verified against PlatformLicensing and PlatformOverview source, including their pricing data.
- [S3] SAMFCore — Features (opens in a new tab)
Functional software scope; deployment integrations still require scoping.
- [S4] SAMFCore — Crypto & Digital Assets (opens in a new tab)
Wallet, exchange and provider-dependent digital-asset workflows.
- [S5] SAMFCore — Perpetual Software Licence (opens in a new tab)
Usage rights and growth economics; not IP ownership.
- [S6] SAMFCore — API & Integrations (opens in a new tab)
Integration framework, not a promise every provider is already connected.
- [S7] SAMFCore — Why SAMFCore (opens in a new tab)
Vendor positioning and technical/commercial control.
- [S8] SAMFCore — Switch to SAMFCore (opens in a new tab)
Migration and scope qualifications.
- [C1] Crassula — Official Platform Website (opens in a new tab)
Vendor-described white-label financial platform and integrations.
- [C2] Crassula — Crypto Product (opens in a new tab)
Vendor-described crypto capabilities.
- [C3] Crassula Help — What Is Crassula? (opens in a new tab)
Product documentation and platform context.
- [C4] Crassula Help — Crassula Apps (opens in a new tab)
Application and administration documentation.
- [D1] SDK.finance — Source Code (opens in a new tab)
Source-code offer; different from SaaS.
- [D2] SDK.finance — Pricing (opens in a new tab)
Commercial options; confirm the selected package in writing.
- [D3] SDK.finance — SaaS Pricing (opens in a new tab)
Advertised €5,500/month plus €0.05/transaction; not lifetime source-code pricing.
- [D4] SDK.finance — FAQ (opens in a new tab)
Vendor answers; package distinctions and terms must be confirmed.
- [D5] SDK.finance — Crypto Banking Solution (opens in a new tab)
Crypto solution positioning and scope.
- [D6] SDK.finance — Acquiring Source Code (opens in a new tab)
Annual/lifetime and one-country licence wording; signed scope controls.
- [V1] Velmie — Delivery (opens in a new tab)
Cloud/on-premise, full source code and full-IP vendor language.
- [V2] Velmie — White-Label Fintech Platform (opens in a new tab)
Digital-banking and fintech delivery positioning.
- [V3] Velmie — Digital Assets (opens in a new tab)
Digital-asset solution scope.
- [B1] Baseella — Official Website (opens in a new tab)
Vendor-described integrated modular core banking platform, cloud/on-premises delivery and advertised pricing headline.
- [B2] Baseella — Core Banking Software Price (opens in a new tab)
Advertised €8,000/€10,000/€12,000 monthly cloud plans, one-time deployment fees and a €600,000 source-code licence; prices are stated to be indicative.
- [B3] Baseella — Core Banking System Features (opens in a new tab)
Vendor-described modules for accounting, payments, cards, compliance, CRM and customer applications.
- [B4] Baseella — Multicurrency, Revaluation & FX Operations (opens in a new tab)
Fiat/crypto balances in one account and a native exchange engine posting into the general ledger.
- [B5] Baseella — Payment Orchestration & Processing (opens in a new tab)
Advertised payment rails, pre-settlement controls and ledger posting; platform accounting wording, not client charges.
- [B6] Baseella — Core Finance (opens in a new tab)
IFRS/FRS102 accounting, double-entry general ledger and multicurrency customer accounts.
- [B7] Baseella — Architecture & Infrastructure (opens in a new tab)
Dedicated instances on AWS, Google Cloud, Azure or Kubernetes-compatible environments, including on-premise.
- [B8] Baseella — Business Operations (opens in a new tab)
Stated audience of EMIs, PIs, MSBs, neobanks, crypto providers and licensed PayTechs.
- [R1] FINMA — Types of Licensing (opens in a new tab)
Swiss authorisation categories; not approval of any compared software.
We did not use network-owned comparison sites as independent corroboration. “Not confirmed publicly” describes the limits of this source review, not the absence of a feature or contractual option. There are no independent ratings, timing benchmarks, savings guarantees or claims of regulator endorsement. This English guide adds no purported translations or language alternates.